
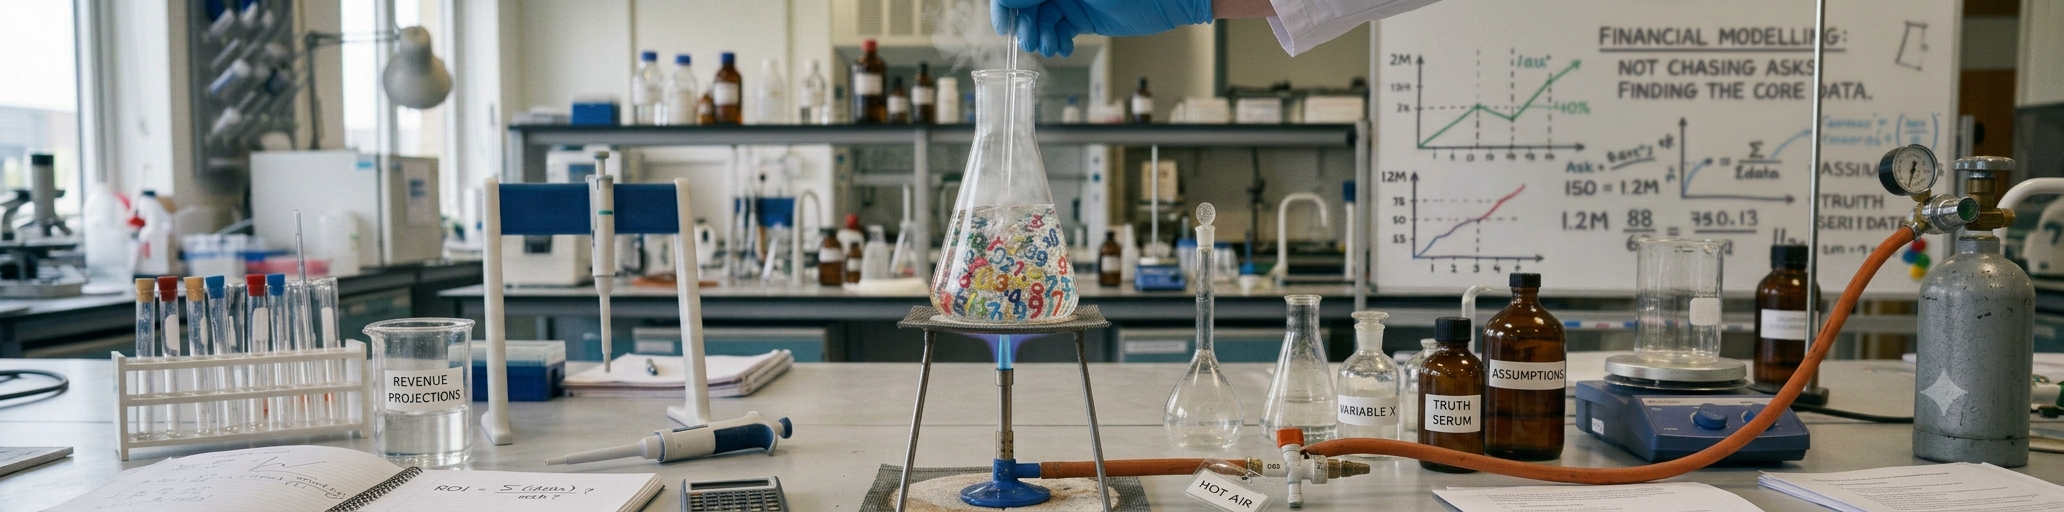
If all financial models are wrong, why bother in the first place?
Our Cambridge Angels member Matthew Cleevely digs into some key questions that founders ask.
Our Cambridge Angels member Matthew Cleevely digs into some key questions that founders ask.
“How far out should I forecast?”
“When do investors expect breakeven?”
“Over what period should revenue be projected?”
I get asked variations of these questions a lot whenever I talk about financial models. The temptation to answer “that’s Numberwang” is strong, but I’m usually more helpful than that. The more boring but much more useful answer is: if your model is mainly being built for what you imagine investors want, you are probably building the wrong kind of model. The tail is wagging the dog.
As this is finance-adjacent, I should do the usual disclaimer fun. This is not advice. You need to make up your own mind. If you do something truly stupid with a spreadsheet, that’s on you.
My more substantive disclaimer is that all financial models are wrong anyway. It’s a fact not a criticism. A model is not a crystal ball. It’s a simplified story of how cash, and sometimes value more broadly, flows in and out of your business in the future, told in numbers. You build one to answer specific questions about possible futures of your business.
The questions that matter are things like:
How am I actually going to get customers? How much will they really pay?
How many people do I need to hire, to get what done?
How much money do I need, and what exactly does it get me?
What happens if things go wrong? If I can’t raise after this round how can I manage my spend?
What things will tell me that I need to cut back?
Those are useful questions because they force you to think about what your business actually is, what drives it, what builds value, and what could kill it. A good financial model is really just a way of making those questions explicit and then forcing yourself to put a story-in-numbers next to the answers.
That is also why modelling is iterative. You build a model to answer a question for a specific audience, look at what it tells that audience, then realise you’ve asked the wrong question or used the wrong mechanics, and go round again. My first model is usually extremely detailed, does everything and is mostly useless. Then I come back to it, realise it answered the wrong thing, throw out most of it, and build the one I actually needed. The simpler the model, the easier that iterative loop is. Your own job as founder is hard enough without building a spreadsheet cathedral you can’t explain. The circle goes questions >models>audience>answers… then back round again.
For founders, the first audience for the model is you. That matters. You need to understand the mechanics of your business and how cash moves through it. Investors come second. Employees come later, when you need targets and operating numbers. HMRC gets a special mention for EIS/SEIS and related joys. But if the founder cannot use the model to provide clarity it’s performative investor theatre - and investors don’t like that.
When I look at an early-stage model as an angel, I’m not really trying to work out whether the spreadsheet is “correct”. It won’t be. What I’m trying to work out is more basic answers to my own questions about a business:
Does this founder understand how value gets created in this business / market?
Do they understand what it costs to build, sell and deliver what they’re proposing, have they thought about it?
How much cash do they need to get to the next meaningful milestone? What happens then?
What does the revenue and value profile of this business look like and is it realistic given the plan?
Investors want to see future value expressed in numbers they can consume as a story that goes along with the pitch deck (aka a plan!). In software that value is usually easiest to express through revenue. In deep tech it may be patents, approvals, contracts, data, technical milestones, regulatory progress, or some other form of de-risking that makes later value creation believable. But the underlying question is the same: where is value coming from, how much and when and what are the activities you do to build it?
This is also why TAM, SAM and SOM can be really useful but are usually closer to bullshit decorative. They are useful if they show that you’ve anchored ambition to a real market and a credible route into it. They are decorative if they are just reaaaally big numbers in a slide deck. Most markets are huge in the abstract. What matters is if someone has understood it and their place within it and can define their specific segment and how they can build a business in it. Understood, defined, and there is a plausible mechanism for getting at it. If you understand your market, you should be able to get a realistic meaningful percentage of it (10-20%) with some reasonable sales paths. Not 0.1% of a $trn market or 100% of a $bn one.
If the honest answers are not venture-scale, you probably do not have a VC business. That is fine. It is much better to discover that in a spreadsheet than after two years of trying to contort your company into a shape it was never supposed to be. Likewise if you can find that you can grow your business without investment even better - go bootstrap!
So, back to those practical questions.
How far out should you forecast?
My answer is: in detail for as long as you need to understand when you run out of money. Usually enough to understand the next 12–24 months properly, and far enough beyond that to show what the business could become. Monthly detail matters in the short run, because that is where reality is: hiring, payment timing, sales cycles, cash burn, the point at which things start going wrong. Beyond that it’s painting a picture of the direction of travel and your understanding of it. Detailed nearer term, then longer-range visibility beyond that, but only report what you can actually narrate.
How soon do investors expect breakeven?
Usually the wrong question. Or at least the wrong first question.
Angels do not all sit there waiting for a universal breakeven date. What matters more is whether the company is using cash to get somewhere meaningful. Product-market fit. Technical de-risking. A real commercial engine. Some evidence that the thing being built will be worth materially more later than it is now. Breakeven can matter a lot in some businesses and much less in others. What always matters is whether the founder knows what the money is buying, why that creates value and to whom in the market.
Whilst you’re here, it’s worth pointing out a few common traps I see a lot in models themselves.
1) Founders get hypnotised by exact numbers. Year 5 revenue of £23,458,392.67. Lovely. Meaningless. Precision is fake confidence. Round numbers are usually better.
2) Build beautiful centreline models where everything goes perfectly. Nothing goes perfectly. Model what happens when growth is slower, CAC is worse, hiring takes longer, churn is uglier, or the next round arrives six months late. That is sensitivity analysis: what does the business look like when things go wrong? It is one of the few ways you can tell whether you understand what actually breaks it.
3) Assume revenue scales while costs politely stay where they are. They do not. Costs scale often much faster than people expect - go look at scaled industry players and their cost bases, it’ll give you a good idea of a realistic mix of your business ‘at scale’.
4) Complex, brilliant, and completely useless model: incredibly detailed, beautifully formatted, and completely unusable. If you can’t explain it, simplify it until you can.
So what does “good” look like?
Honestly, much simpler than most founders think. A summary tab. The key question stated. Assumptions visible. Outputs visible quickly. At least one reality check. Something you can actually change and see the result from. Someone else can understand it. And you can describe what it shows in a few sentences. That’s a decent model. It can be as little as a single table with entirely manual numbers. It does not need to be a spreadsheet opera - lots of founders think it needs to be, it’ll get there, but that’s when you can afford a CFO and some accounting agents.
So all financial models are wrong. But that doesn’t make them useless. They are tools for asking better questions, understanding where reality bites, and deciding what kind of business you are actually trying to build and how to resource it.
Finalists announced for Cambridge Tech Week 2026 Pitching Competition
Five of the UK’s most innovative startups have been selected to compete in the live Cambridge Tech Week Pitching Competition this September.
Jamie Urquhart leaves a rich legacy, says Arm founder Hermann Hauser
Arm founder Dr Hermann Hauser has outlined the crucial role played by engineer Jamie Urquhart who died recently but left a rich legacy to technology and the broader business community.
Defensibility and Moats in AI: A Cambridge Angel Perspective
"How do I prove defensibility?" This is a question Cambridge Angels hears from a number of AI founders. In a landscape where today's breakthrough risks becoming tomorrow's commodity, Cambridge Angels member Chris Mitchell has helpfully provided his views on what separates fundable AI ventures from the rest of the pack.
"How do I prove defensibility?" This is a question Cambridge Angels hears from a number of AI founders. In a landscape where today's breakthrough risks becoming tomorrow's commodity, Cambridge Angels member Chris Mitchell has helpfully provided his views on what separates fundable AI ventures from the rest of the pack.
Cambridge Angels evaluates AI opportunities by looking beyond the hype to identify sustainable competitive advantages. In an era of rapid technological shifts, defining and demonstrating a "moat" is critical for long-term viability.
1. AI Definition: Beyond LLMs to the Broader Field
When Cambridge Angels discusses AI, the definition extends far beyond Large Language Models (LLMs). While generative AI and LLMs are current focal points, "defensible" AI often involves the broader field, including physical AI, computer vision, and specialized machine learning. For instance, some companies utilize computational physics and proprietary algorithms for post-RGB machine vision, representing a more specialized application of AI than general-purpose text generation. Similarly, other firms focus on transforming unstructured medical records into validated legal insight applying AI to complex, regulated domains.
2. Speed of Development and Breakthrough Vulnerability
The speed of development in AI means that today’s breakthrough can quickly become tomorrow’s commodity. Moats are dynamic; they can evaporate as technology breakthroughs happen. A key risk is the "Good Enough" competitor: an enterprise might prefer a 70% effective, easily deployable LLM-based solution over a complex, 100% effective solver-based engine. Investors look for companies that can maintain a lead despite the rapid pace of the industry, often through continuous innovation or deep technical integration that is not easily replicated by general updates to foundational models.
3. Categories of Moats and Defensiveness
Defensiveness in AI can fall into several categories:
Proprietary Data: A library of well-characterized, unique data that competitors cannot easily access is a primary moat.
Technical/IP Moats: Patents on specific approaches, such as novel approaches to Quantum Key Distribution, provide legal barriers to entry.
Hardware-Software Co-design: Deep integration between novel hardware (like metasurfaces) and proprietary algorithms creates a complex barrier that software-only players cannot easily hurdle.
Regulatory/Clinical Validation: In sectors like healthcare, having a platform that is already approved for sensitive patient data and clinically validated creates a significant "beachhead".
4. Evolution of Moats Over Time
A company’s moat typically evolves as it matures. Initially, the moat may be purely technical or IP-based - the "secret sauce" of a research spinout for example. As the company scales, the value can often shift toward the data accumulated through operations and the deep integration into customer workflows. For example, a company providing autonomous enterprise operations might start with a unique technical solver, but its long-term defensibility will come from the "world-model" it builds using specific customer data, which becomes increasingly difficult for a new entrant to replace.
5. Demonstrating a moat
To effectively demonstrate a moat, founders must provide concrete evidence of sustainable competitive advantages. This includes technical performance benchmarks that showcase superior capabilities, robust customer validation such as successful paid pilots with major industrial firms, and where appropriate a clear, well-defined IP strategy. Ultimately, proving a moat requires showing a "decisive competitive edge"—the specific, technical, or operational reason why even a well-funded competitor cannot easily displace the solution.
Battle-tested playbooks for five leadership conundrums
Advice from business titans who have been there before.
Capitalise #18 – The best technology disappears
For the March issue of our Capitalise newsletter, Pierre Socha uncovers the hidden technology that makes modern life possible.
Cambridge and London dominate innovation rankings through patent power
Cambridge and London each provide four of the top 10 in a new UK league table highlighting the power bases for innovation based on the strength of their Intellectual Property assets.
How to pitch your IP without giving away the secret sauce. PART 3 OF 3: Proving IP Value Without Revealing the Secret Sauce
Series Preface
This article is part of a three-part series on how founders can pitch intellectual property convincingly without revealing their “secret sauce”, written by IT technologist and angel investor Dr Anthony Harris.
Author Bio
Anthony has been a member of Cambridge Angels since 2019. Before that he was a member of Cambridge Capital Group (CCG) and continues as a member of the Oxford Capital co-investor circle. He has been angel investing for over twenty years, has invested in more than fifty companies, and is somewhat unusual in that he makes a living out of angel investing as well as investing in the capital markets (he was an early-stage investor in Amazon, PayPal, Google, Microsoft, PayPal, Motorola, Apple, Palantir and many other tech success stories). According to him he does this by ‘investing in things I know with a few fun investments along the way’ (Flit, and Oxitec being just two examples). Anthony originally studied computing at Oxford Brookes (when it was Oxford Polytechnic) and then went on to work in R&D and development in the computing industry (mainframes and microcomputers), including some time working in Silicon Valley. In 1989 he founded Software 2000, an OEM software house which he used to suggest was ‘the most successful company you’ve never heard of’. The company’s royalty and licensing business transformed inkjet and connected laser printer technologies world-wide, won four Queen’s awards for export, numerous other industry awards, and grew to $150m valuation with offices in three continents. Anthony exited in 2007 to a management buy-out and went on to study for an MA at Oxford, an MA(Res) at Reading and his PhD at Cambridge (Sidney Sussex). He has been mentoring on the ‘Accelerate’ programme at the Judge Business School since 2014 and continues to help start-ups with advice on intellectual property and business finance. He has just finished a research fellowship at Clare Hall (Cambridge) and is now a fellow and director of studies for computer science at Emmanuel College (Cambridge). Anthony sits on the board of Cambridge Angels as our treasurer and is on the boards of Flit and ScaleXP, two Cambridge Angels portfolio companies.
In Part 1 of this series, Anthony set out the core pitching challenge founders face when trying to explain what makes their technology valuable and defensible. In Part 2, he examined why patents are often the default response — and why, particularly for technology and software businesses, they can unintentionally weaken defensibility rather than strengthen it.
You can read the earlier pieces here:
Part 1: www.cambridgeangels.com/news-ecosystem/how-to-pitch-your-ip-without-giving-away-the-secret-sauce-some-part1
Part 2: www.cambridgeangels.com/news-ecosystem/how-to-pitch-your-ip-without-giving-away-the-secret-sauce-some-part2
Proving Value Without Revealing Details
Sophisticated founders don’t say to investors, ‘trust us, we have great IP.’ Instead, they show structured evidence of a defensible competitive advantage. This is the real pitch advantage of a trade secrets strategy because it’s something you can talk about openly when chatting to investors.
A well-executed trade secrets programme demonstrates several things to investors:
First: It proves that you understand your own IP. You've identified those aspects of your technology that provide competitive advantage. You've categorized your confidential information, core algorithms, manufacturing processes, business methods, customer data, and market approaches. You've thought strategically about what elements of your business need protecting versus what can be public-facing. Investors notice this rigour. It signals you're not just haphazardly protecting everything; you're thinking like a scaled business that understands its IP assets.
Second: it demonstrates defensive capability. You've implemented robust non-disclosure agreements between employees, contractors, and partners. You've built a security infrastructure appropriate to the value of your secrets. You've created documented processes for maintaining confidentiality. When presented as a structured trade secrets programme, this becomes visible proof that you're defensible against competitive threats, talent poaching, and other IP risks.
Third: it makes your valuation more robust. When your data room includes evidence of a thoughtful trade secrets strategy, including indexed and categorized confidential information, NDAs, security protocols, documented history of IP protection, then investors take it seriously. That intellectual property becomes quantifiable value on the balance sheet. Exit valuations can be materially affected by the quality and defensibility of your IP, and a properly structured trade secrets programme demonstrates real, transferable value.
Most importantly: with trade secrets investors don't need to know your secret sauce. They just need confidence that you have a secret sauce and that you're protecting it seriously. Of course, there is always a risk that a competitor may come along later and patent what you have been doing for some years. That’s why it is important to keep innovating and continually moving the technological goalposts so that by the time they arrive where you are you will be waving at them from a distance. Trade secrets are not a good solution if you intend to rest on your laurels and stay where you are. Note that the original Coca-Cola recipe may have remained a trade-secret but they are always innovating recipes, bottle designs, flavours etc. etc.
When Disclosure Actually Hurts You
Consider the alternative: if you patent core technology, you've just handed detailed technical specifications to every competitor, every potential acquirer, and every patent troll with access to a search database. If your exit scenario involves acquisition by a strategic buyer, they might use that publicly available patent information to design around your technology or develop competing approaches. If you're bootstrapping and bootstrapped, you've incurred significant costs for protection that potentially makes you less defensible, not more.
For software in particular, the problem is acute. Software patents face eligibility challenges and many innovations simply don't qualify for patent protection. The technical specifications required for patent prosecution might reveal implementation details that competitors could adapt. The exclusivity period of 20 years may be longer than the period that your technology remains commercially relevant. Hence, you would've spent significant resources protecting something that will become commoditised well before the patent expires.
The Practical Approach: Know Your Audience
Here's where strategy meets execution. Different stakeholders need different assurances:
For Investors: Focus on demonstrating structured IP thinking. Show categorized confidential information, explain your rationale for trade secret protection in your specific market, and present concrete evidence of security measures. This reassures investors you are building real defensibility. You're not hiding behind vague claims of ‘proprietary technology’ but instead are demonstrating a sophisticated, and well-thought-out, IP strategy.
For Partners and Contractors: Robust CDAs/NDAs are your tool. These should clearly define what information is confidential, how it can be used, and what happens if it's misused. Well-drafted CDAs/NDAs are extraordinarily effective at creating legally binding confidentiality without requiring public disclosure. Remember to identify everything that you deem CONFIDENTIAL in the legal documentation and to mark everything CONFIDENTIAL that you send out to them.
For Acquirers: Your data room should give a comprehensive story of your IP. Evidence of your programme of trade secrets, the breadth and depth of protected information, security measures, and documented history will all contribute to acquisition value. Buyers value companies that have thoughtfully protected their IP because it means a cleaner acquisition, a lower integration risk, and a clearer ownership of valuable assets.
The Hybrid IP Advantage
The most sophisticated approach to IP employs a mixture of patents and trade secrets (as with the example of the Aero chocolate bar). For example, you might decide to patent broad architectural approaches or specific novel technical innovations, the aspects that define your solution category. All the while maintaining as trade secrets the specific implementation details, algorithms, data structures, and processes that would take competitors significant time and resources to reverse engineer and duplicate. This approach gives you the public recognition and competitive advantage of patents while preserving the indefinite, disclosed-free protection of trade secrets. You control exactly what the world sees, and what remains hidden.
The Disciplined Execution
However, trade secrets come with their own challenge in that they require discipline. You cannot be sloppy about confidentiality and still claim protection. Employees, contractors, and partners need clear understanding of what's confidential and why. For example, documents associated your secret sauce should be marked appropriately. Access should be restricted to it, normally through a small subset of members of trusted staff. NDAs should be signed before confidential information is shared, confidential information should be marked as CONFIDENTIAL (it often isn’t!), and your IT security should match the value of what you're protecting. These procedures are not onerous for a small team as it's largely common sense assuming that it is applied consistently. However, it does require attention and you need someone thinking about it, even if that someone is just your founder.
Making the Pitch
So, the next time that you send a pitch for vetting, and hopefully get to present to the investors, consider reframing the IP conversation. Rather than leading with patents (which immediately raises questions about disclosure and defensibility), present your strategy as a thoughtfully structured trade secrets programme, supplemented by patents where strategically appropriate. Show your investors the specific confidential assets that you have which provide your competitive advantage. Explain how you protect them and why your approach makes your IP defensible. Finish off by explaining what this means for the scalability of your technology as well as your final exit value.
That conversation, anchored in visible, strategic thinking about IP protection, is far more compelling than a vague reference to patent applications and ‘proprietary technology.’ Not only does it demonstrate maturity, strategy, and defensibility but it shows that you are protecting what actually matters. Perhaps more importantly, it helps you to keep your secret sauce exactly where it belongs: secret.
How to pitch your IP without giving away the secret sauce. PART 2 OF 3: The Patent Paradox and the Trade Secret Alternative
Series Preface
This article is part of a three-part series on how founders can pitch intellectual property convincingly without revealing their “secret sauce”, written by IT technologist and angel investor Dr Anthony Harris.
Author Bio
Anthony has been a member of Cambridge Angels since 2019. Before that he was a member of Cambridge Capital Group (CCG) and continues as a member of the Oxford Capital co-investor circle. He has been angel investing for over twenty years, has invested in more than fifty companies, and is somewhat unusual in that he makes a living out of angel investing as well as investing in the capital markets (he was an early-stage investor in Amazon, PayPal, Google, Microsoft, PayPal, Motorola, Apple, Palantir and many other tech success stories). According to him he does this by ‘investing in things I know with a few fun investments along the way’ (Flit, and Oxitec being just two examples). Anthony originally studied computing at Oxford Brookes (when it was Oxford Polytechnic) and then went on to work in R&D and development in the computing industry (mainframes and microcomputers), including some time working in Silicon Valley. In 1989 he founded Software 2000, an OEM software house which he used to suggest was ‘the most successful company you’ve never heard of’. The company’s royalty and licensing business transformed inkjet and connected laser printer technologies world-wide, won four Queen’s awards for export, numerous other industry awards, and grew to $150m valuation with offices in three continents. Anthony exited in 2007 to a management buy-out and went on to study for an MA at Oxford, an MA(Res) at Reading and his PhD at Cambridge (Sidney Sussex). He has been mentoring on the ‘Accelerate’ programme at the Judge Business School since 2014 and continues to help start-ups with advice on intellectual property and business finance. He has just finished a research fellowship at Clare Hall (Cambridge) and is now a fellow and director of studies for computer science at Emmanuel College (Cambridge). Anthony sits on the board of Cambridge Angels as our treasurer and is on the boards of Flit and ScaleXP, two Cambridge Angels portfolio companies.
In Part 1 of this series, Tony explored the “pitching conundrum” founders face: how to clearly explain what their product does and why it is defensible, while navigating opaque vetting processes and pitching to sophisticated investors without giving away the secret sauce.
You can read Part 1 here: www.cambridgeangels.com/news-ecosystem/how-to-pitch-your-ip-without-giving-away-the-secret-sauce-some-part1
The Patent Paradox
Many founders default to patents as the answer, because patents are a familiar choice and having a patent, or ‘patent applied for’, feels like proper IP protection. Patents carry prestige and are often one of the first things that investors ask about. They also have recognisable value and can often be capitalised to add substance to a young company’s balance sheet. Many investors are unwilling to enter into confidential disclosure agreements (CDAs/NDAs) so having a patent gives a measure of strong IP protection when pitching to an unknown audience. However, there is alternative approach to filing patents (trade secrets) which, if executed well, can make a company more valuable to investors, not less. Before discussing trade secrets it is important to understand the pro’s and con’s associated with patents.
The uncomfortable truth about patents is that at some point along the way they require inventors to tell the world exactly how their technology works. Filing a patent means eventually disclosing your invention in sufficient detail that someone ‘skilled in the art’ (i.e. an expert in your field) could theoretically reproduce it. That full specification becomes publicly available through publication, normally 12-18 months after filing, regardless of whether your patent is ultimately granted or not. There is really no alternative to ‘full disclosure’ of the invention in the patent application because a common defence in patent litigation is ‘non-reproducibility’. In other words, if somebody can demonstrate that your invention cannot be reproduced using the details in your published patent then they can apply for it to be struck out. It is a mark of an inexperienced founder/inventor to suggest that they have only disclosed ‘some’ of their invention. Such a comment would normally make me very unlikely to invest in the venture.
For a software company, this publication/disclosure rule is particularly problematic. Software patents are difficult enough to apply for and get granted but the patent must describe your algorithms, data structures, and specific implementation choices in enough detail so that somebody else can do what you do. Obviously, these are the exact details that constitute your competitive advantage and, once this information is published, then your competitors can study it, reproduce it, potentially design around it, and even create variations themselves that replicate your tech, but maybe from a different angle. It’s a risk whichever way you look at it.
Patents also come with a significant price tag. Filing, prosecution, and maintenance of a single patent can easily cost thousands in the UK, and substantially more in the US, Europe, and beyond. That's before considering the time overhead: managing the prosecution process, responding to examiner rejections, and maintaining the patent portfolio over many years if you want global protection. When the patent eventually expires your IP is free for anyone to use so that, for many technology companies, this feels less like protection and more like an expiration date on your competitive advantage.
The Trade Secret Alternative
Trade secrets operate on fundamentally different principles to patents. They represent confidential business information (including your algorithms, methods, and data), that provide your competitive advantage and which remain undisclosed outside of your company. There's no patent office, no formal registration, no expiration date. As long as you maintain confidentiality and can demonstrate that you took reasonable steps to protect it, your trade secret remains protected indefinitely. Internally you need to restrict access to your trade secrets and to document how you do that. In my own company we developed proprietary imaging/halftoning technology, a novel imaging pipeline (based on display-list technology), and a colour management system. These were well ahead of other technologies in the market and so we wanted to keep them as our ‘trade secrets’ rather than publishing what we were doing. This strategy worked well for us because once competitors had worked out what we were doing, we had already innovated beyond our previous techniques and shifted the goalposts.
Probably one of the best known examples of a trade secret is the formula for Coca-Cola. Despite it being one of the world's most valuable trade secrets for over a century, Coca-Cola have never patented it. They have kept it confidential, protected it through NDAs, and physically restricted access to it. That strategy has served them better than any patent would have because the moment you patent a formula; the world knows the formula exists and eventually gets to use it. By keeping it secret, Coca-Cola have preserved their competitive advantage permanently. A similar example is the Aero chocolate bar where the chocolate recipe is not documented but you can find an ancillary patent which explains how to generate bubbles in chocolate by using nitrogen in a reduced pressure environment. So, in this case, one aspect of the technique is protected through a patent but the chocolate recipe remains a ‘trade secret’.
For technology startups the flexibility offered by a trade secret is extraordinary. You are not forced to choose between disclosure (patenting) and no protection (keeping quiet) so you can actually demonstrate robust IP protection to investors without surrendering your technological secrets. What is not to like!
In Part 3 of this series, Anthony explains how founders can prove IP value, defensibility, and exit potential without revealing the details that actually matter.
How to pitch your IP without giving away the secret sauce. PART 1 OF 3: The Pitching Conundrum – Getting Past the First Two Hurdles
Series Preface
This article is part of a three-part series on how founders can pitch intellectual property convincingly without revealing their “secret sauce”, written by IT technologist and angel investor Dr Anthony Harris. Across the series, Anthony explores the realities founders face when pitching to investors, the risks and rewards of patents versus trade secrets, and how to demonstrate IP value without over-disclosure.
Author Bio
Anthony has been a member of Cambridge Angels since 2019. Before that he was a member of Cambridge Capital Group (CCG) and continues as a member of the Oxford Capital co-investor circle. He has been angel investing for over twenty years, has invested in more than fifty companies, and is somewhat unusual in that he makes a living out of angel investing as well as investing in the capital markets (he was an early-stage investor in Amazon, PayPal, Google, Microsoft, PayPal, Motorola, Apple, Palantir and many other tech success stories). According to him he does this by ‘investing in things I know with a few fun investments along the way’ (Flit, and Oxitec being just two examples). Anthony originally studied computing at Oxford Brookes (when it was Oxford Polytechnic) and then went on to work in R&D and development in the computing industry (mainframes and microcomputers), including some time working in Silicon Valley. In 1989 he founded Software 2000, an OEM software house which he used to suggest was ‘the most successful company you’ve never heard of’. The company’s royalty and licensing business transformed inkjet and connected laser printer technologies world-wide, won four Queen’s awards for export, numerous other industry awards, and grew to $150m valuation with offices in three continents. Anthony exited in 2007 to a management buy-out and went on to study for an MA at Oxford, an MA(Res) at Reading and his PhD at Cambridge (Sidney Sussex). He has been mentoring on the ‘Accelerate’ programme at the Judge Business School since 2014 and continues to help start-ups with advice on intellectual property and business finance. He has just finished a research fellowship at Clare Hall (Cambridge) and is now a fellow and director of studies for computer science at Emmanuel College (Cambridge). Anthony sits on the board of Cambridge Angels as our treasurer and is on the boards of Flit and ScaleXP, two Cambridge Angels portfolio companies.
The Pitching Conundrum
The First Hurdle (Vetting) - Getting to the Pitch
It is unusual for early-stage founders to be able to talk directly to a business angel or VC analyst. Normally there is a front-end vetting process that they must go through where their pitch is sifted, by a person or persons unknown, from the hundreds or (sometimes) thousands sent to angel groups or VCs each year. Because the vetting process is, by its very nature, opaque founders don’t really know who will see their pitch deck first. As a result, they tend to be overly reticent about their product and its ‘secret sauce’. Hence, many pitch decks sent in for vetting don’t end up answering the crucial question, ‘What is it and what makes it unique?’ Founders fear putting this in a first-approach pitch deck because they don’t know where it will end up or who will see it but this means many pitch decks never get past this first hurdle because the front-end vetting team can’t work out what it does. The logic here is that if the founders can’t explain what their product does in simple terms, then they will be laughed at when/if they get in front of an angel group or VC investment panel and the vetting team will be left with egg on their faces if it did get through their process. Hence, to grab attention and to make a deck stand out it is extremely important to explain succinctly what the product does and why what it does is important (and hopefully unique). This means also explaining that there is a high cost of entry to competitors entering the market and doing the same thing quicker and cheaper! High costs of entry can be demonstrated through ‘patent(s) applied for’, ‘patent(s) granted’, ‘trade-secrets’, or ‘it’s demonstrably difficult’ (e.g. a unique hardware design that has taken years to develop, Quantum, or AGI). It’s worth-while having a couple of slides in the initial deck which state ‘here exactly is what it is’ and ‘here’s why it’s difficult for somebody else to do exactly what we do’. Generally, pitches that deal with this up-front are the ones that pass the vetting process and get moved on to pitch to the investors. ‘Many are called but few are chosen’ so it is important to get things right at this stage.
The Second Hurdle (The Pitch)
When founders pass the vetting process and do eventually get to pitch directly to investors, they naturally want to demonstrate the value of their product and its intellectual property. This means further justifying the valuation, demonstrating its defensibility in concrete terms, and validating the high cost of entry for potential competitors. Yet they are also acutely aware that the people they are pitching to will understand their market in some depth, have valuable networks directly in their area of expertise, and might not be the investors that they ultimately end up with. Hence the ‘pitching conundrum’. How much do they reveal without giving away the farm and how do they prove they have got something genuinely defensible without handing potential competitors a complete instruction manual of how to do what they are doing (or intend to do)?
Many founders default to patents as the answer, because patents are a familiar choice and having a patent, or ‘patent applied for’, feels like proper IP protection. But is this always the right choice?
In Part 2 of this series, Anthony explores why patents are often the default response to this conundrum — and why that default may be more dangerous than founders realise.
The Perse School hosts Sherry Coutu CBE for AI in education networking event
We were thrilled to host Sherry Coutu CBE – serial entrepreneur, angel investor and Co-Chair of AI in Education (AiEd Certified) – at The Perse School this week for our AI in Education networking event.
In conversation with David Cleevely: Serendipity: It Doesn't Happen by Accident
In our latest In Conversation Academy session we were joined by David Cleevely, a telecoms pioneer, deep tech investor, and one of the driving forces behind the Cambridge tech cluster, as he shares insights from his new book, Serendipity: It Doesn't Happen by Accident.
ACF Investors: Why raising EIS limits is a budget imperative
The Budget offers a golden opportunity for the UK government to reaffirm its commitment to building a world-class technology ecosystem. Successive administrations since the global financial crisis of 2008 have recognised the importance of high-growth companies in reviving the economy. The logic is sound: build an environment where startups can grow into global leaders like the fintech pioneers Monzo, Wise, and Revolut, and Britain will reap the economic benefits.
T-Therapeutics announces Series A extension to $91 million to advance first-in-class bispecifics towards the clinic
$32 million new equity injection adds to previously announced $59 million
New investors Tencent and BGF joined by all existing major shareholders
Funds will advance pipeline of novel TCR-CD3 bispecifics in cancer and autoimmune disease
Paying it forward: The trailblazing Cambridge entrepreneurs engineering the next wave of global innovators
Cambridge’s global reputation for science and technology isn’t just built on invention. Innovation is actively engineered and fine-tuned here in the city - and nowhere is this more evident than on the Impulse programme, the University of Cambridge’s flagship entrepreneurship initiative.
Cambridge Angels CEO has earned her wings and then some!
Emmi Nicholl has just been promoted to CEO at Cambridge Angels. Tony Quested posed some key questions.
Awards adds influence to Cambridge's bid for global greatness
Big-name companies are piling in as sponsors of the annual Business Weekly Awards to help a united Cambridge gain more traction on the global stage. Innovate Cambridge and Cambridge Innovation Capital are using the Awards to highlight their open gateway promotion to showcase light blue research to the wider world.

Birketts polishes gem of a deal between Sapphire France and US group FlexXray
Law firm Birketts has advised the shareholders of Sapphire France Holdings Limited on the sale of the main business and its subsidiary companies across both the UK and France to FlexXray in Arlington, Texas – a leading provider of food safety and inspection services.

VolkerFitzpatrick to deliver new development phase at St John’s Innovation Park
St John’s College has appointed VolkerFitzpatrick to deliver the next phase of expansion at St John’s Innovation Park in Cambridge.
Cambridge Innovation Capital pledges £100m+ for University spin-outs
Cambridge Innovation Capital (CIC) is pledging mega-money and mentorship to take more spin-outs out of the university and put them on the road to global success.